A payment label does not confirm that deposits or withdrawals work, or that an offshore casino can lawfully serve Australians.
“PayID accepted” sounds like a simple yes-or-no statement. I used to treat payment labels that way: if a page named a method, I assumed I could use it. But a label is only useful when it clearly refers to the service being offered, and when the operator’s position can be checked. For Australian players, there is a more basic issue to keep in view before treating any offshore casino’s payment claim as an invitation.
The Interactive Gambling Act 2001 prohibits operators from offering online casino games to people in Australia. It does not explicitly make it a crime for an individual to use an offshore site, but that distinction does not turn the service into a lawful, locally protected option. Australian consumer law does not protect players using offshore casinos. A payment method shown on a page does not change either point.
That’s the line I’d keep clear: a site may claim to support PayID, but that claim is separate from whether it may lawfully offer online casino gambling to Australians, and separate again from what protection you would have if something went wrong. One question is about the payment label. The other is about the service and the risks around it. Mixing them together makes the label sound more reassuring than it is.
When you’re looking for an online casino that accepts PayID in Australia, check the payment options at the casino before depositing, as they can change. These brief notes highlight the details available for each operator.
Bizzo Casino
You can note Bizzo Casino’s listed licence: the Curacao Gaming Control Board, held by TechSolutions Group N.V.
Playfina Casino
You can note Playfina Casino’s Curacao eGaming licence, held by Hollycorn N.V. since 2017. Its minimum deposit is A$20–30, depending on the offer.
DragonSlots Casino
You can note DragonSlots Casino’s Curacao Gaming Authority licence, held by Jumpman Gaming Ltd.
Wild Tokyo
You can note Wild Tokyo’s Curacao licence and A$10 minimum deposit. Its listed payout times are 30–60 minutes for crypto and 1–5 days for fiat.
JustCasino
You can note JustCasino’s Curacao Gaming Control Board licence.
Roby Casino
You can note Roby Casino’s Curacao eGaming licence, held by Roby Games Ltd.
Vegaz Casino
You can note Vegaz Casino’s Curacao licence, OGL/2024/1335/0780, and its minimum deposit of EUR 20.
Rollero Casino
You can note Rollero Casino’s Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
SkyCrown
You can note SkyCrown’s Tobique Gaming Commission licence and A$30 minimum deposit. Its listed payout times are around 10–15 minutes for crypto and 1–5 days for fiat.
Golden Pokies
You can note that Golden Pokies is listed as holding a Curacao licence.
For “PayID accepted” to mean something concrete, it would need to identify the relevant operator and make clear that PayID is supported for the particular service and for customers in Australia. A passing mention on a page, a logo, or a broad statement about payment options does not, by itself, establish those details. Nor does a method being familiar in everyday banking prove it is available at a casino.
I’m not going to describe any operator as an Australian casino that accepts PayID. That would turn an unsubstantiated payment label into a recommendation by implication. It would also blur the legal boundary: an offshore site’s claimed payment support is not evidence that it is authorised to offer online casino games to people in Australia. “Accepted” is not the same as “approved.” Two different claims.
This matters even when the wording is dressed up as “best” or “trusted.” Those are sales words, not proof. If a page says PayID is available, the sensible reading is only that the page makes that claim. It does not establish that the claim is current, that it applies to an Australian customer, or that using the service comes with Australian consumer protection. I would not let a payment badge do the work of answering questions it was never designed to answer.
It is easy to focus on the practical appeal of paying through a familiar method and miss the bigger question. I’ve made that kind of mistake with gambling promotions: a smooth-looking checkout can make the whole offer feel more solid than it is. But the payment route does not provide a local safeguard if the operator is offshore. Australian consumer law does not protect players who use offshore casinos.
The law also draws an important distinction between the operator and the individual player. The Interactive Gambling Act 2001 prohibits operators from offering online casino games to people in Australia, while not explicitly criminalising a player for using an offshore site. That distinction should not be stretched into a claim that offshore play is lawful, endorsed, or protected. It simply describes different treatment of operators and players.
So when you see a claim that a site accepts PayID, don’t read it as a signal that the site is safe for Australians, legally available, or backed by local consumer protections. It says nothing about those things. The payment claim and the legal position sit alongside each other, but they are not interchangeable.
I know the temptation: a familiar payment name can make an unfamiliar gambling site seem less risky. I’ve learned not to confuse a recognisable checkout with a dependable service. A payment method cannot fix the legal status of the offer, and it cannot create consumer protections that do not apply. Keep those questions separate. That’s the useful first check.
Legal Risk
Australian consumer law does not protect players using offshore casinos, and the Interactive Gambling Act 2001 prohibits operators from offering these services in Australia.
A “best PayID casino” list sounds like it should make the decision easy: a few names, a quick comparison, done. I’d be wary of that neatness. A ranking is only useful if its entries are supported by clear, current evidence that the named service accepts PayID. I can’t responsibly name or rank any Australian-facing casino on that basis.
That isn’t a small gap you can fill by trusting a confident headline. A page can repeat the words “PayID accepted” without showing what the statement rests on. The claim might be old, vague, or about a different product or part of a service. Without evidence that ties PayID to the specific operator and the specific claim, a list of “top” sites would be dressing uncertainty up as advice.
I’ve made the mistake of treating tidy tables as proof. They look like someone has checked everything; often, all they tell you is that someone has arranged claims into columns. The layout isn’t evidence. Neither is a bold badge, a star rating, or a line saying a site is a good choice for PayID deposits.
A comparison can report what it has actually established. It can say which operators it checked, what evidence it used, and when it checked it. If it doesn’t make those things clear, the ranking can’t tell you whether the PayID claim is current or even specific to the service being described.
That distinction matters because “accepts PayID” can be used loosely. It may appear in a heading while the supporting text discusses payments generally, or it may be repeated from another page without independent confirmation. That does not prove the claim is false. It does mean the wording alone is not enough to establish that PayID is accepted.
The same goes for pages that use “best” as if it were a measurable finding. Best by what standard? A payment claim alone cannot establish that a site is reliable, lawful, suitable, or safe for you. Those are different questions, and a list that bundles them together without showing its basis is doing more than the evidence can support.
So I wouldn’t turn a search for casinos that accept PayID into a shortlist simply because several pages use similar wording. Repetition can make a claim feel settled. It doesn’t make it verified. I’d want to see a specific statement from the relevant operator, presented clearly enough to distinguish PayID from other payment methods, and I would still treat that as a claim to assess rather than an endorsement.
There are no PayID-supported casino operators I can responsibly put forward as confirmed choices for Australian readers. Naming a few anyway would create the impression that they had passed a check they have not passed here. Leaving names out is less satisfying than a ranked list, but it is more honest than filling the page with guesses.
This is also why I would not swap in a list of sites that accept another payment method. A card, wallet, or bank-linked service is not evidence of PayID support. Nor does a general claim about deposits establish that a particular method is available. Similar-sounding payment language is easy to blur when a page is trying to look comprehensive.
There is a wider issue behind these claims. The Interactive Gambling Act sets the boundary for online casino services offered to people in Australia, and the Australian Communications and Media Authority is responsible for enforcing that law. A payment label does not change the legal status of a service. It also does not turn a promotional ranking into a reliable verification process.
That is not a reason to assume every payment statement is false. It is a reason to keep the scope narrow: a claim about PayID should be treated as a claim about PayID, not as proof that the operator is suitable or that using the service is protected. I would not use a payment method as a shortcut for judging the rest.
When you encounter a page promising the best PayID sites, look for a clear account of what was checked and what the claim actually covers. If the page offers names but no convincing basis for those names, don’t let the ranking do the thinking for you. I’d rather leave a blank than send someone toward an unverified option.
Not a recommendation.
A PayID label beside a deposit option is only a starting point. Before committing money, I’d want the actual payment instructions in front of me and a clear answer about what happens after I submit them. The wording on a button can look reassuring; the details are what matter.
Start with the cashier. Is PayID presented as an available deposit method for your account, or is it mentioned somewhere else on the site? Don’t treat a general payment logo, an old help page or a search result as confirmation that the method is available at the point you are trying to pay. If the option is not shown clearly, pause rather than guessing how to make it work.
Then read the instructions from beginning to end. Look for the information you would need to make the payment correctly, including the recipient details, the amount and currency accepted, and any reference you are told to include. Check that the instructions match what appears in the payment app or banking service before approving anything. If the details change between screens or are unclear, don’t try to fill in the blanks yourself.
I would also check the conditions attached to the deposit. Is there a stated minimum or maximum? Does the site say whether a fee applies, or whether the amount will be credited in full? Is the deposit described as immediate, or does it need to be reviewed first? Those are questions to get answered before paying, not after money has left your account. If the terms don’t spell them out, don’t assume the answer is favourable.
Processing time deserves its own check. A payment method’s name does not tell you when a casino will show a deposit in your balance. Look for an explanation of what “pending” means, whether you receive a receipt or confirmation, and what steps are described if the payment leaves your account but the balance does not update. A vague promise of a quick deposit is not a useful procedure.
There’s another practical detail that’s easy to overlook: the account name or recipient shown during payment. It should make sense in relation to the instructions you were given. If you’re asked to send money to a recipient that doesn’t match the explanation, or to follow instructions through an unexpected channel, stop and seek clarification through a contact route you reached independently. Don’t rely on a message that appears mid-transaction to explain away a mismatch.
I’ve learned not to confuse a smooth-looking cashier with a clear one. Before paying, I want the amount, recipient, any required reference, possible charges and expected processing explained plainly. Keep a record of the instructions and any confirmation you receive, but don’t send a payment just to see whether the process works. That turns uncertainty into a real money problem.
If you cannot get straightforward answers, leave the transaction alone. You don’t need to resolve uncertainty by making a deposit. A method may appear in a menu while its practical terms remain unclear, and a successful-looking payment screen does not by itself explain what will happen next. Stop there.
When I see a payment method attached to an online casino, I have to keep two questions apart: how the site says you can pay, and whether it is lawful for that service to offer casino gambling to someone in Australia. PayID, a bank transfer or a card cannot change the legal status of the service.
The Interactive Gambling Act 2001 makes it illegal for operators to provide real-money online casino games to people physically in Australia. The rule concerns the operator offering the service; it does not explicitly make an Australian player’s use of an offshore site a criminal offence. That distinction matters, but it is not a stamp of approval or a sign that playing is protected.
The Australian Communications and Media Authority, usually shortened to ACMA, is the regulator that enforces the Act. Its role is directed at prohibited services and the operators providing them. So a website’s claim that it takes PayID does not establish that it can lawfully offer casino gambling here, or that ACMA has approved it. A payment button is not a licence. It is just a payment claim.
I used to treat a familiar-looking cashier as a reassuring sign. That was a bad shortcut. A site can present itself neatly, name a payment option and accept a transaction without giving you the protections you might expect from an Australian-regulated service. Australian consumer law does not protect players who use offshore casinos. If something goes wrong, you should not assume that local consumer protections will step in simply because you live here or paid from an Australian account.
That is the part people can miss while looking up a casino that accepts PayID in Australia. The wording makes the practical payment question feel like the main issue. It is not. Whether a site takes PayID and whether it may offer real-money casino gambling to Australian residents are separate matters. Neither claim proves the other.
I would also be careful with language such as “available to Australians”. It may describe what a website allows technically, not what Australian law permits the operator to provide. A site loading on your screen, or displaying Australian currency or a local payment option, does not settle that legal question. Access is not approval.
This is not me saying that players are criminally liable for using an offshore casino; the Act does not explicitly criminalise players in that situation. It is me refusing to turn that narrower point into reassurance. The operator’s legal position and your practical position as a customer are different things. If the operator is offshore, Australian consumer law does not provide the protection you may assume comes with an ordinary local purchase.
So when a casino says it accepts PayID, read that only as a statement about a payment method, if it is accurate at all. Do not treat it as evidence that the casino is lawful to offer here, regulated locally, or able to resolve a dispute under Australian consumer protections. Those are separate questions, and a payment option answers none of them. Keep that line clear.
A payment method and a game catalogue answer different questions. Seeing PayID mentioned beside a casino does not tell you what the service offers, whether any particular game is available, or whether it can lawfully be provided to someone in Australia. Those claims need to be considered separately.
I used to treat a familiar payment logo as a kind of reassurance: if the cashier looked straightforward, I assumed the rest of the site was just as clear. That was a bad shortcut. A payment label says nothing by itself about the operator’s services or the legal position. “PayID games” may sound like one combined feature, but the payment route does not define the games.
The boundary for operators in Australia is important. Under the Interactive Gambling Act 2001, it is illegal for operators to provide real-money online casino games to people physically located in Australia. The law does not explicitly criminalise a player for using an offshore site, but that is not the same as saying the service is lawful or protected. Australian consumer law does not protect players who use offshore casinos. A payment option cannot change either point.
So, when you see a claim linking PayID to casino play, don’t read it as proof that a particular service or game is suitable for Australian residents. It may only be a claim about how money is handled. Even if a site presents payment details and game information on the same page, one does not verify the other.
There is also a practical difference between a service saying that a payment method is available and being able to establish what the service actually offers. A reference to PayID is not evidence of a particular catalogue, and a catalogue description would not establish that the operator may legally provide those services in Australia. Keep those questions apart. It is less tidy than a single “all-in-one” promise, but it is more honest.
I’d be wary of wording that bundles payment and play into one attractive label. It can make a claim feel more complete than it is. The useful distinction is simple: payment information concerns a transaction; game information concerns the service being offered; Australian law concerns what operators may provide to people here. None of those answers automatically supplies the others.
The law’s focus on operators does not turn an offshore site into a locally protected option for players. Nor does a payment method create that protection. If a page makes the payment sound like a stamp of approval, I’d slow down and read the claim narrowly. A cashier feature is not a legal clearance.
PayID can look like the obvious thing to search for when you want a bank-linked way to pay, but Australian payment habits are not built around one option. People move between cards, mobile wallets and services connected to bank accounts, including PayPal. That flexibility is ordinary here; it does not tell you what a particular website accepts.
Contactless credit and debit cards are accepted almost everywhere in Australia. Google Pay and Apple Pay have similarly broad acceptance. Those are useful facts about day-to-day payments, not a shortcut for working out whether an online casino supports PayID. A payment method being familiar in shops or other services does not establish that it is available in a casino cashier.
I’ve made that leap before: if a method is everywhere in ordinary life, I assumed it would carry over online. It doesn’t follow. “Widely accepted” describes the general payment landscape, not every merchant, service or transaction. A bank-linked option such as PayPal belongs in that broader mix, but its presence in the market still says nothing by itself about PayID availability at a casino.
That distinction matters because payment pages can make a site seem more straightforward than it is. A list of familiar methods is not proof that each one works for Australian customers, and an Australian payment habit is not evidence of a casino’s actual arrangements. Keep those ideas separate. Broad habit, narrow claim.
There is another boundary worth keeping in view: Australian consumer law does not protect players who use offshore casinos. Familiar payment tools do not change that position or make an offshore gambling service locally protected. The payment method and the legal status of the service are separate issues.
So, when you encounter a claim about an Australian casino using PayID, don’t infer acceptance from how common contactless cards, Apple Pay, Google Pay or bank-linked services are across the country. Those options show that Australians are comfortable switching between payment types. They do not confirm that a casino accepts PayID. Familiarity is not confirmation.
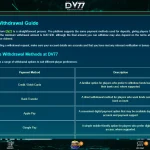
A payment option for adding money and a route for getting winnings out are separate things. Even if a casino’s cashier shows PayID for deposits, that alone tells you nothing about whether withdrawals can be sent to PayID. I’ve learnt not to treat one button in a cashier as a promise about the whole payment journey.
Before you rely on a PayID withdrawal, look for the operator’s actual withdrawal terms. Check whether PayID is named for payouts, whether the account must first be verified, and whether the casino requires you to withdraw by the same method used to deposit. Read the terms that apply to withdrawals, not just the deposit instructions or a banner listing payment methods.
Attention: A PayID deposit option does not guarantee that withdrawals can be made via PayID; always check the specific payout terms first.
The label “instant withdrawal” needs the same scrutiny. It may sound like the money arrives immediately, but a payment method’s name does not establish how quickly a casino approves and sends a payout. Processing can involve the casino’s own checks, and the displayed time may not describe the time until funds reach your account. Don’t plan around a promised speed unless the relevant terms clearly explain what it covers.
Keep a copy of the cashier details and the withdrawal rules you relied on. If PayID appears in one place but not the other, ask the operator to clarify before you deposit. Save the response. A vague assurance is not the same as a clear payout policy.
There is another boundary worth keeping in view: Australian consumer law does not protect players using offshore casinos. A payment route, even one that appears familiar, does not change that. Nor does it make an offshore service lawful for operators to provide to people in Australia. The Interactive Gambling Act 2001 prohibits operators from offering real-money online casino games to people physically located here.
So treat “PayID supported” and “PayID withdrawals available” as distinct claims, and don’t let an advertised deposit option stand in for a payout rule. Check the withdrawal terms before making a decision. No guesswork.
A PayID label beside a real-money casino claim can sound like a complete answer: the site takes the payment, the account is available to Australians, and the service is legitimate to use. Those are separate questions. A payment claim alone does not establish that an Australian player can access the service or that the operator may legally offer it here. I would not treat a PayID mention as proof of a verified real-money option.
The legal boundary matters more than the wording on a cashier page. Under the Interactive Gambling Act 2001, operators must not offer online casino games to people in Australia. That prohibition covers the operator’s conduct; the law does not explicitly make a player’s use of an offshore site a criminal offence. But that distinction is not a green light. Australian consumer law does not protect players using offshore casinos, and a payment method does not change that position.
I have seen how easy it is to read a familiar payment name as reassurance. It is not. Whether a site claims to accept PayID says nothing by itself about its legal status, consumer protections, or whether a real-money service is actually available to you. Nor does the phrase “PayID casino” turn an offshore offer into something authorised in Australia.
That applies whether the claim mentions a debit-linked payment, a payout route, or a promotion tied to a deposit. Each is a separate claim, and none makes the underlying service lawful. I would keep the distinction plain: payment method on one side, permission to provide online casino gambling to Australians on the other. They do not merge.
The careful answer is not a list of supposed real-money PayID casinos. It is that a PayID claim cannot establish a verified option for Australians, and it cannot remove the legal and consumer risks attached to offshore gambling. The operator is the one barred from offering the service here; players are not explicitly criminalised simply for using an offshore site. Still, there is no Australian consumer-law safety net for that choice.
A familiar payment name can make an offer feel ordinary. It doesn’t make it safe.
I’ve learned not to treat a payment label as a shortcut to knowing how a transaction works. A card has familiar steps: it can be selected in a cashier, card details and an amount entered, then the payment submitted. That tells you something about card payments. It tells you nothing about whether a casino accepts PayID or what a PayID transaction there would involve.
The same goes for Amex. A casino might handle card deposits differently from withdrawals, and an issuer may block a gambling transaction. Those are card-specific considerations, not a template for PayID. Seeing a card payment described as instant, fee-free or subject to a particular limit is no basis for expecting the same from a different method.
“PayID accepted” can sound reassuring, but the phrase alone does not tell you whether it refers to deposits, withdrawals, or both. It also does not establish any transaction steps, fees, limits or processing time. I would not fill those gaps by borrowing details from card payments. Different rails, different rules.
There is another distinction worth keeping clear: a payment method does not make an online casino lawful or protected. Australian law prohibits operators from providing real-money online casino services to people in Australia. Australian consumer law does not protect players who use offshore casinos. A payment label cannot change either point.
So if you are trying to work out whether a casino takes PayID, don’t read card details as confirmation. And don’t treat the words “pay with PayID” as proof of how a payment will work. The sensible conclusion is narrower: card information only describes cards. No leap of faith.
A payment method and a promotion are separate claims. Even if a site says it accepts PayID, that alone tells you nothing about whether a deposit made that way qualifies for a bonus, whether a no-deposit offer exists, or what conditions apply. I’ve learned not to treat a bright “bonus” label as an answer. It is only a label.
A genuine promotion would need clear terms explaining eligibility and the required payment method. Without those details, there’s no sound basis for assuming that PayID is included. Nor should you read a mention of PayID alongside a bonus as proof that the two are connected. They may simply appear on the same page.
There is a more important limit in Australia. The Interactive Gambling Act 2001 bars operators from providing real-money online casino games to people in Australia. The law targets operators; it does not explicitly make a player’s use of an offshore site a criminal offence. But Australian consumer law does not protect you when you use an offshore casino. A promised promotion does not change that position or make a service safe.
I would be especially wary of claims that make a PayID casino bonus sound automatic, guaranteed, or risk-free. Promotional wording can leave out important conditions, and a bonus claim is not evidence that an operator may lawfully provide casino gambling here. Australian rules also restrict advertising online casino services, so promotional claims should not be treated as an invitation to sign up or deposit.
No shortcut here. A PayID reference cannot establish that a bonus exists, that you qualify, or that the underlying service is lawful for Australians. If the claim does not clearly connect the payment method to the promotion, don’t fill in the gap yourself.
Each casino sets its own Amex deposit and withdrawal limits, so they vary by operator. Check the limits shown by the casino before making a transaction.
Amex deposits are processed instantly. Withdrawals can take up to five days to clear.
Using Amex does not give you Australian consumer protection when gambling with an offshore casino. The Interactive Gambling Act prohibits operators from offering online casino games to Australian residents, and a payment method does not change that.
Yes. The casino sets the Amex deposit and withdrawal limits, and they vary between operators.
Some casinos do not allow withdrawals to Amex, and you generally need to have made a previous deposit with Amex to withdraw to it. Offshore casinos are not protected by Australian consumer law.
Amex may block payments to a particular website, and Australian banks may also block gambling transactions on Amex cards. Some casinos do not accept Amex.