Payment labels do not establish legality or guarantee that the same route works for deposits and withdrawals.
A payment button can make a site look ready to take your money. That tells you only what the operator claims to accept; it does not make the service lawful in Australia or mean the route is suitable for every transaction. I learned to stop treating a polished cashier as proof that the important details had been sorted.
The legal starting point matters more than the menu. Under the Interactive Gambling Act 2001, providing real-money online casino games, including pokies and table games, to people in Australia is illegal for operators. An offshore licence does not make that service compliant with Australian law. So the payment categories discussed in specialist reviews are not recommendations to fund an online casino account. They are labels you may encounter when assessing claims—and a reason to pause before sending money.
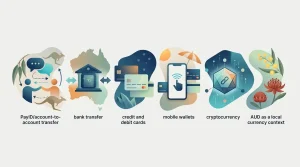
Those categories can include bank transfers, e-wallets, prepaid vouchers and cryptocurrency. They work differently, but a list of logos does not tell you what protections, restrictions or practical limits apply. Nor does it establish that a payment provider permits the transaction. A casino payment solution is not a magic bridge around Australian law, a bank’s decision or a provider’s own terms.
When choosing an online casino payment option, you should check the practical details that are available, such as deposit minimums and payout timing. This list highlights the payment-related information provided for each operator without assuming details that are not stated.
Bizzo Casino
Bizzo Casino is listed with a Curacao Gaming Control Board license held by TechSolutions Group N.V. The available information does not specify its payment methods or processing times.
Playfina Casino
Playfina Casino lists a minimum deposit of A$20–30, depending on the offer. It is licensed by Curacao eGaming, with Hollycorn N.V. holding the license since 2017.
DragonSlots Casino
DragonSlots Casino is listed with a Curacao Gaming Authority license held by Jumpman Gaming Ltd. No payment methods, deposit minimums, or payout times are specified.
Wild Tokyo
Wild Tokyo lists crypto payouts in 30–60 minutes and fiat payouts in 1–5 days, with a minimum deposit of A$10. Its listed license is from Curacao.
JustCasino
JustCasino is listed with a Curacao Gaming Control Board license. The available details do not specify its payment methods or transaction timing.
Roby Casino
Roby Casino is listed with a Curacao eGaming license held by Roby Games Ltd. No payment-specific details are provided.
Vegaz Casino
Vegaz Casino lists a minimum deposit of EUR 20 and a Curacao license, OGL/2024/1335/0780. The available information does not state its payment methods or payout timing.
Rollero Casino
Rollero Casino is listed with Curacao Gaming Control Board license OGL/2023/176/0095, held by Hollycorn N.V. No payment-specific details are provided.
SkyCrown
SkyCrown lists crypto payouts in approximately 10–15 minutes and fiat payouts in 1–5 days, with a minimum deposit of A$30. Its listed license is from the Tobique Gaming Commission.
Golden Pokies
Golden Pokies is listed with a Curacao license. The available information does not specify its payment methods, deposit minimum, or payout timing.
Bank-linked payments can appear familiar because they connect to an account you already use. E-wallets hold money within a separate service. Prepaid vouchers limit spending to the amount loaded, though that does not make the underlying gambling service lawful. Cryptocurrency is a different case again: it is not a permitted deposit method for online wagering in Australia. A page offering a “Bitcoin payment” should not be read as a safe or lawful invitation to transfer funds.
That distinction gets blurred in sales copy. “Instant” means the site is describing a step in its own process, not promising that every institution involved will accept or complete it. “More choice” can simply mean more logos. And an option visible on a phone is still only an option displayed by the operator; it does not show that the route is authorised for online casino gambling in Australia.
I used to focus on what the cashier made easy. That was the wrong end of the decision. The useful questions are whether the service itself can lawfully be offered where you are, what the payment provider’s terms say, and whether the button is available for the specific transaction you have in mind. A method’s name alone cannot answer those questions.
 Safe Online Pokies in Australia: What to CheckLearn what offshore licences do—and don’t—protect, how PayID and Bitcoin affect payments, and why the Interactive Gambling Act 2001 matters.
 Casinos That Accept Ethereum in Australia: What to CheckLearn what general claims about Ethereum payments can and can’t confirm, including why potentially fast transactions and limited fees are not guarantees.
You may also see searches and promotions about Bitcoin, Revolut, Volt or a phone payment casino. Treat those as separate claims, not interchangeable solutions. A brand name in a payment list does not prove current availability, local approval or permission to use it for casino gambling. The same goes for cryptocurrency as a broad category: a site may display it, but that does not make it a lawful deposit route for online wagering in Australia.
I would not call any of these Australian casino payment options a “best” choice for funding an offshore casino. That label skips the central issue. Real-money online casino services are prohibited for operators in Australia, and offshore access or a foreign licence does not change that position. Before acting on a payment prompt, consider whether you should be using the service at all—not just which button looks quickest.
The method is not the safeguard. A familiar bank logo, a wallet name or a voucher cannot turn an unlawful service into a lawful one, and a payment page is not evidence that Australian consumer protections cover an offshore casino balance. I have made the mistake of reading convenience as reassurance. It isn’t.
The amount shown beside a deposit button tells you little about how you could get money back. A specialist review notes that the methods offered for deposits may differ from those available for withdrawals. Treat that as a detail to verify for a particular operator, not a rule that applies everywhere. A payment route that gets money into an account is not automatically an exit route.
Attention: A payment route that allows you to deposit funds is not automatically an exit route for withdrawals.
I used to read a payment page as if it were a two-way promise. It isn’t. The operator may list a method for adding funds while setting different conditions for cashouts, or may not offer that method for withdrawals at all. The practical question is not simply, “Can I pay this way?” It is whether the same operator will return funds through a route you can actually use.
That distinction matters because a deposit and a withdrawal are separate transactions. Each has its own selection of methods and may involve different steps. A displayed option is not enough to establish that it works both ways. Nor does a successful deposit settle what happens when you ask to withdraw. Check the cashout route before committing money; finding out later is a rotten time to discover the mismatch.
There is also a broader issue that comes before payment mechanics. Under Australia’s Interactive Gambling Act 2001, it is illegal for operators to provide real-money online casino games to people physically located in Australia. That includes pokies and table games. Payment information should not be mistaken for approval, a recommendation, or evidence that an offshore service is lawful here. I’m describing the mechanics, not suggesting that Australians use such services.
For a large cashout, bank transfer may be worth considering despite its slower pace. A specialist review describes it as a possible fit for withdrawals over $10,000. That is a specific assessment, not a guarantee that every operator offers bank transfers at that level, or that every request will be processed the same way. The amount alone does not tell you whether the route is available to you.
“Suitable” can sound like “better,” but those are not the same thing. A bank transfer may make sense when the withdrawal is substantial and you can wait; speed may matter more in another situation. I wouldn’t choose a route based only on how quickly the deposit appears. The cashout side deserves equal weight, and the operator’s stated conditions matter more than a sales label.
Before treating any payment option as a plan, read the withdrawal terms and check that they apply to the method you intend to use. Look for whether the route is offered for cashouts, what conditions attach to it, and whether the operator can change the available options. Keep the distinction clear: a payment page shows what is presented at that moment, not necessarily a lasting promise.
This is basic casino payment risk management: decide how money could leave before considering how it could go in. It won’t make an unlawful service lawful, and it won’t remove the possibility of delays or changed conditions. But it can stop one avoidable mistake—assuming that an easy deposit means an equally easy withdrawal.
Read both directions. Short version.
PayID is not a separate bank account or a wallet you have to top up. It lets a bank account be identified through a mobile number, email address or Australian Business Number (ABN), with payments moving through the New Payments Platform. That connection is what makes PayID recognisable to many Australians: every major Australian bank supports it.
PayID allows a bank account to be identified through a mobile number, email address or Australian Business Number (ABN) via the New Payments Platform.
That broad bank support can make the method look straightforward. The catch is that your bank supporting PayID does not mean a particular gambling operator accepts it, or that every PayID transaction will work in the same direction. A specialist review reports that operator support can vary, with deposit availability needing to be checked separately from withdrawal support. Treat that as a prompt to inspect the actual payment terms, not as a standing guarantee about the whole market.
I learned not to stop at the deposit screen. It might show a PayID option and still leave you needing a different route to receive money back. Before you enter bank details or send funds, look for the operator’s stated withdrawal methods and any conditions attached to them. If the wording is unclear, ask the operator directly and keep its answer. A logo in a payment menu is not a cashout promise.
A specialist review characterises PayID as the primary Australian-dollar deposit route at many offshore operators. That is a description of reported operator practice, not evidence that a service is lawful in Australia. The distinction matters: under the Interactive Gambling Act 2001, operators cannot provide real-money online casino services to people located in Australia. Payment access does not change that legal position, and an offshore payment option is not proof of local approval.
For ordinary bank use, the basic idea is familiar: a PayID points to a bank account rather than asking you to remember a long set of account details. Check that the name and payment instructions shown by the recipient match what you expect before confirming anything. If a transaction is redirected, or the displayed recipient does not make sense, pause rather than assuming that the payment page is correct. A small moment of checking beats trying to unwind a transfer later.
There is another detail that is easy to miss. PayID’s link to a bank account can make a payment feel like a direct bank transaction, but the operator’s own processing rules still matter. The bank connection alone does not tell you whether a deposit will be credited, whether withdrawals are available through the same route, or how long an operator will take to handle a request. Read the method’s terms at the point where you would actually use it.
I used to treat a familiar payment name as a shortcut for trust. That was lazy. The payment rail and the service accepting the payment are separate things: PayID tells you how a bank payment may be addressed, not whether the recipient is appropriate or whether a later withdrawal will follow the same path. Keep those questions separate.
So, when checking PayID, confirm three things in the operator’s current terms: whether it accepts PayID deposits, whether it supports PayID withdrawals, and whether the account details and conditions are clear before you proceed. Do not infer the answers from your bank’s support for PayID or from the presence of a button. Bank compatibility is only one piece. The exit matters too.
A payment button can make a transfer look like one clean step. It isn’t. There may be a payment gateway between the operator’s cashier and the bank, and then a separate internal check before the account balance or withdrawal is updated. The screen can say “submitted” while the money is still moving through those stages. I learned not to treat a confirmation message as proof that everything has settled.
Some casinos may charge a flat bank-transfer fee of $5–$15. Additionally, converting balances from euros (EUR) to Australian dollars (AUD) can result in a deduction of 2–4%.
For a bank withdrawal, the operator may need to review and release the request before the bank can process it. A specialist review describes one arrangement where withdrawals are handled manually once or twice a week; under that schedule, a request made on Friday could arrive by Wednesday. That is an example of a particular operator’s process, not a timetable you can assume applies elsewhere. The useful detail is that weekends and a limited processing schedule can matter even when the bank transfer itself is straightforward.
Fees can also appear at different points. A specialist review reports that some casinos charge a flat bank-transfer fee of $5–$15. Check whether the fee is taken from the amount requested or added separately, if the cashier explains this. A small line in the terms can change what reaches your account. Annoying, but worth checking.
Currency conversion is another quiet deduction. If a balance is held or paid in euros rather than Australian dollars, converting AUD to EUR can cost 2–4%. The displayed balance and the amount that lands in your bank account may therefore differ. Before confirming a transaction, look for the settlement currency and any conversion terms; don’t assume the figure shown in the cashier is the final amount in your account.
This is where “instant” can be a slippery label. A gateway may pass payment information quickly, but that does not tell you how long an operator takes to review a withdrawal, whether a bank handles it on a particular schedule, or what conversion costs apply. The payment technology is only one part of the route. The hand-off matters.
I’d read the cashier details and payment terms together, rather than relying on the button’s wording. Look for processing schedules, transfer charges and the currency used for settlement. If those details are vague, contact support before sending money and keep the answer. A clear explanation is more useful than a reassuring badge.
This is not a recommendation to use an offshore casino. Real-money online casino services are illegal for operators to provide to people in Australia under the Interactive Gambling Act 2001. But understanding how a payment is processed still helps you spot misleading language and avoid assuming that a submitted request is already complete.
Small print, real money.
BPAY is a slower bank-payment route, not a way to get funds ready for immediate play. A specialist review describes BPAY payments as taking one to two business days. That is a meaningful wait if you are expecting a balance to appear straight away, so I would not treat the word “payment” as a promise of instant availability.
The same kind of review presents BPAY as a possible fallback when PayID is unavailable, and says it is rarely used for real-time gameplay. That makes its role fairly narrow: it may be listed as another route, but it is not a like-for-like substitute for an option intended to move a payment promptly. If PayID is unavailable, BPAY may be offered as an alternative; the trade-off is time.
Legal Prohibition
Under the Interactive Gambling Act 2001, it is illegal for operators to provide real-money online casino games to people physically located in Australia.
I used to skim a payment page, spot a familiar bank option and assume the money would be there when I wanted it. That was the wrong way to read it. The method’s name tells you little about when a payment will be usable. With BPAY, the stated processing window is the detail that matters. A business-day estimate is not an instant confirmation, and it leaves room for a wait before the transaction is reflected.
Nor does seeing BPAY in a casino payment system tell you that it will work for every purpose. A payment option can be described for money going in without establishing that it is available for other transaction types. Keep the question focused: what does the payment page say BPAY does, and when does it say the funds should arrive? Do not fill in gaps from the method’s presence alone.
This is not a reason to treat a slower route as a safer one. The label says how a payment may be made; it does not, by itself, establish that an operator is lawful or that a transaction is protected. In Australia, the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in the country. A payment description does not change that legal position.
So if you encounter BPAY in a listing, read it as a delayed bank-payment option, not a shortcut. The one-to-two-business-day timing and its stated backup role when PayID is unavailable are the useful points. I would not choose it expecting a real-time balance, and I would not infer more from a payment menu than it actually says.
Slow route. Different job.
A payment portal can look reassuring: familiar logos, a tidy list of ways to pay, and a button that appears to move money straight into an account. I used to treat that screen as proof the whole transaction was sorted. It isn’t. A deposit option says nothing by itself about whether there is a workable way to withdraw, what checks may be required, or whether the service is lawful for someone in Australia.
That last point matters more than the layout of the portal. Under the Interactive Gambling Act 2001, operators cannot provide real-money online casino games to people physically located in Australia. A foreign licence or an available payment button does not make an offshore casino legally authorised to serve Australians. So don’t use a payment page as a green light to deposit. Short version: a button proves very little.
If you are checking a casino payment portal for general information, look for separate, plain-language terms for deposits and withdrawals. The route shown beside “pay in” may not be offered beside “cash out”. Check the conditions before relying on a method, and don’t assume a brand appearing in a menu means it can handle both directions. This applies whether the page mentions a bank route, an e-wallet, a voucher or another service.
The identity side can also interrupt a withdrawal. A specialist review says an operator may ask for government-issued identification, proof of address dated within three months, and evidence that the payment method belongs to you. That is not a promise that every operator asks for the same documents, or that sending them will resolve every delay. It is a reminder to read the stated verification terms before sharing personal information. If the request is unclear, don’t guess what to upload.
I’d also separate “verified” from “safe”. A document request does not make an offshore service compliant with Australian law, and an operator’s payment instructions are not a guarantee that funds are protected under Australian consumer law. Don’t send sensitive documents through an unfamiliar link or reply channel; use only contact details independently confirmed from the service’s own site, and stop if the instructions don’t match its published terms.
This is where the phrase “easy cashout” can do a lot of work without answering much. Read the withdrawal rules, the identity requirements and the payment-method conditions as separate things. If any are missing or contradictory, that’s a reason to pause—not a puzzle you need to solve by making a deposit first.
For Australians, the practical check ends before funding: real-money online casino services are prohibited when offered to people in the country. No payment method changes that. A payment portal may describe how an operator handles transactions, but it cannot turn an unlawful service into an authorised one. Keep your money and identity documents out of that process.
An e-wallet can make the route between a payment account and a casino balance look simple. The part I pay attention to is what happens when money leaves: the provider’s transfer time is only one piece, and a fee can take a bite before funds reach a bank account.
A specialist review describes MuchBetter withdrawals as quicker than a conventional bank cashout. The same review gives a possible wait of as long as five days for a bank transfer. That comparison is useful as a pointer, not a promise: processing can depend on the operator and the payment arrangement, so check the specific withdrawal terms rather than treating a provider’s name as a timing guarantee.
Skrill has a different cost to watch. A specialist review says a Skrill withdrawal to a bank can take one to two days, and that some casinos apply a transaction charge of one to three per cent. “Fast” can still mean waiting for the bank leg, and a percentage fee means the amount deducted rises with the transfer. I’d check whether the charge comes from the operator or Skrill, and whether the displayed amount is before or after it.
Neteller needs a separate distinction. A specialist review reports a 1.45% charge when funding Neteller by credit card. That is a cost attached to card funding, not a reason to use a credit card for online gambling: Australian rules prohibit providing real-money online casino services to people in Australia, and credit cards are not an acceptable casino deposit route. Don’t confuse a wallet’s funding options with a permitted way to pay for wagering.
Withdrawals are described as quicker than conventional bank cashouts.
Bank transfers can take one to two days, with some casinos applying a 1–3% transaction charge.
Funding the wallet by credit card may incur a 1.45% charge.
The wallet name alone does not settle the full cost. Check the casino payment provider’s terms for withdrawal fees, bank-transfer charges and any conversion that could change the amount received. Then compare the stated time for the wallet transfer with the separate time for a bank withdrawal. A quick arrival in an e-wallet does not mean the money is already in your bank.
I learned to stop reading “low-cost” as “cost-free.” A provider may have its own charge, while the operator may set another one; the quoted processing window may also begin only after the operator releases a withdrawal. Keep a record of the fee and the amount shown before confirming, so the final bank credit does not come as a surprise. Small print matters.
For Australians, this is information for assessing payment claims, not an invitation to use an offshore casino. The Interactive Gambling Act 2001 makes it illegal for operators to provide real-money online casino games to people physically in Australia. A fast wallet cannot change that legal position.
“Instant” sounds like a promise about the whole transaction. It often describes only one stage: the payment being authorised. A specialist review describes Visa and Mastercard deposits as instant, but that label does not mean an Australian card payment to an offshore casino will go through. Australian financial institutions block many standard card transactions to offshore casinos. The button can be there; the bank can still say no.
That distinction matters. A payment page may present a familiar card option as part of its casino payment integration, but seeing Visa or Mastercard listed is not evidence that your bank will accept the transaction. I’d treat “instant” as a description of processing when a payment succeeds, not as a guarantee that it can be made. No shortcut there.
Crypto needs a separate warning. It is not a deposit method for online wagering in Australia. If you encounter cryptocurrency in connection with an offshore casino, don’t read that as approval to use it for a deposit. And if you are considering a cryptocurrency withdrawal, remember that a blockchain transfer cannot be reversed once sent. There is no card-style chargeback if the address is wrong or the transaction goes somewhere you did not intend. That is a serious trade-off, not a minor technical detail.
A specialist review puts Litecoin withdrawals at about ten minutes, while Bitcoin can take up to an hour when its network is congested. Those are reported processing times, not a promise about how quickly an operator will approve or send a withdrawal. Network conditions can affect the transfer, and the speed alone tells you nothing about the fees or the amount that will arrive. Check those details before making a decision.
The practical point is simple: a quick deposit label does not settle whether a payment will work, and a fast blockchain transfer does not make crypto reversible or suitable for depositing. Read the payment terms carefully, keep the withdrawal route in view, and don’t mistake a familiar logo for a functioning payment option. “Instant” has limits.
A prepaid voucher gives you a firm spending ceiling: once you have used the value loaded onto it, there is nothing more to spend from that voucher. That can help you keep a payment separate from your everyday account. It does not, though, make the voucher a way to receive money back.
That is the part I’d check before treating “paying via a voucher” as a complete payment route. Voucher payments generally cannot be returned to the voucher as a cashout. If money is due back, another withdrawal method is needed. The voucher’s spending limit is useful for controlling what leaves your hands; it does not solve how funds could leave an account.
Different tools get lumped together under “digital wallet”, but that label doesn’t make them interchangeable. Paysafecard and Neosurf are voucher-based options, while other services may store or move money differently. A payment app’s presence on a screen is not evidence that it can be used to withdraw. Paysafecard, Neosurf, Apple Pay and Google Pay are not permitted withdrawal routes. Check the applicable rules rather than assuming a deposit option works in reverse.
PayPal is a separate case. It has prohibited gambling transactions in Australia since 2021, so seeing its name discussed alongside wallets does not make it an available gambling payment option here. Nor does a list that includes PayID, EcoPayz, UPI or ACH establish that those routes are supported or lawful for Australian use. Names travel across payment guides; permissions do not.
There is also a bigger point than the checkout screen. Real-money online casino services, including pokies, are prohibited for operators serving people in Australia under the Interactive Gambling Act 2001. An offshore payment button does not change that legal position. I wouldn’t treat a payment logo, voucher code or app prompt as proof that a service is authorised for Australians.
My own mistake was to judge a method by how easy it looked at the deposit stage. That misses the exit. With vouchers, the spending cap is clear, but the cashout route has to be separate; with wallets, the label alone tells you neither whether a transaction is permitted nor whether it can be used to withdraw. Check the rules before moving money. No shortcut here.
A phone can make the payment step feel almost too simple. A specialist review describes Apple Pay deposits as being made through the phone’s digital wallet, with biometric authentication confirming the action. That is the whole convenience: approve it on the device instead of typing payment details into a form.
But a smooth mobile payment is not proof that the same wallet can receive money back. Apple Pay is not a permitted withdrawal route, so don’t treat it as a complete way to move funds in both directions. If an operator’s payment screen shows Apple Pay, that tells you only what the screen offers for that transaction. It does not settle cashout arrangements.
I learned to separate those two ideas the hard way: a quick tap is a payment feature, not a promise about what happens later. Check the withdrawal route before paying, and don’t assume a phone wallet can replace a bank account or another permitted cashout method.
There’s also a legal point that a glossy mobile checkout can make easy to ignore. Under Australia’s Interactive Gambling Act 2001, providing real-money online casino games to people in Australia is illegal for operators. A familiar wallet, biometric prompt or polished mobile page does not change that. I wouldn’t read payment availability as a sign that an offshore service is lawful here.
If you’re comparing mobile payment options, focus on what the method actually does rather than the word “instant”. Apple Pay’s role here is depositing through a phone wallet; it is not a withdrawal solution. Another named e-wallet, such as MuchBetter, should not be assumed to behave like Apple Pay just because both can appear in conversations about mobile payments. The method and its permitted use are separate questions.
Keep it simple. A tap can be easy; the route out is different.
There is no payment method that makes funding an offshore online casino a suitable choice: Australian law prohibits operators from providing real-money online casino games to people in Australia. A payment option or overseas licence does not change that.
PayID links your mobile number, email address or ABN to an Australian bank account through the New Payments Platform. Whether a casino accepts PayID for deposits depends on the operator, and you should check withdrawal support separately.
Many Australian financial institutions block standard Visa and Mastercard transactions to offshore casinos. A payment option displayed by a casino does not override your bank’s decision or make the service lawful in Australia.
Fees can apply: some casinos charge 1–3% for Skrill transactions, and Neteller charges 1.45% for credit-card funding. Currency conversion from AUD to EUR can also cost 2–4%.
Some casinos charge a flat $5–$15 fee for bank transfers, while crypto withdrawals are usually free. Currency conversion from AUD to EUR can cost 2–4%, and fees may differ between deposit and withdrawal methods.